CIA Part 3 vs Part 2: Scope, Question Style and Study Hours
By PrepHoot Editorial Team· (updated Oct 12, 2026)
If you're searching for cia-part3 while fitting certification prep around work, your practical question is probably which part deserves your next study block. CIA Part 2 centers on carrying out an internal audit engagement. Part 3 centers on running the internal audit function and handling its results. That difference shapes the decisions you practice, the weaknesses you diagnose, and how you allocate study hours.
I'd choose your study sequence by comparing those responsibilities with your current experience. First, though, check the syllabus version. Older descriptions of Part 3 can send you toward the wrong material.
Check which Part 3 syllabus your materials cover
Part 3 preparation depends on the syllabus attached to your exam language and date. A recent publication date alone doesn't establish that a resource covers the right objectives.
EduDelphi
EduDelphi's CIA Exam Format & Syllabus 2026, published September 21, 2026, identifies the 2025 syllabus as current for English-language CIA exams throughout 2026. It reports that English exams transitioned on May 28, 2025, and describes Part 3 as Internal Audit Function.
EduDelphi website screenshot for cia-part3
That makes the guide useful for checking the outline before choosing materials. Its Part 3 coverage emphasizes audit operations, the audit plan, quality, and engagement results and monitoring.
The limitation is straightforward: a syllabus overview can establish what belongs in your preparation, but it doesn't demonstrate your ability to answer unfamiliar questions. Use it as a version check before evaluating a question bank.
The IIA's 2019 Part 2 syllabus is explicitly labeled as an older syllabus. Keep historical outlines separate from your current preparation.
Before buying a resource, inspect its domain names and weights. For Part 3, compare its coverage with the IIA Part 3 syllabus. If its objectives conflict with the version you need, resolve that mismatch before spending time on the questions.
Part 2 follows an engagement; Part 3 oversees the function
The most useful comparison is the level of responsibility each part addresses. Part 2 asks you to think through an individual engagement. Part 3 moves toward decisions affecting the audit function and the treatment of engagement results.
FreeFellow
FreeFellow's CIA Exam Study Guide 2026, published August 29, 2026, provides this weighted breakdown:
FreeFellow website screenshot for cia-part3
For Part 2, Internal Audit Engagement:
- Engagement Planning: 50%.
- Information Gathering, Analysis, and Evaluation: 40%.
- Supervision and Communication: 10%.
For Part 3, Internal Audit Function:
- Internal Audit Operations: 25%.
- Internal Audit Plan: 15%.
- Internal Audit Function Quality: 15%.
- Engagement Results and Monitoring: 45%.
FreeFellow describes Part 2 through engagement objectives, risk assessment, procedures, evidence, and workpapers. Its Part 3 summary covers the risk-based audit plan, quality assurance and improvement, communication of results, follow-up, and escalation.
This makes the guide useful for organizing a diagnostic by domain. Its limitation is that the outline doesn't establish how many hours you personally need. Start with these weights, then adjust your preparation according to errors on unfamiliar questions.
Part 2: connect the objective to the evidence
Based on those objectives, I'd practice Part 2 as a chain of decisions: define the engagement objective, identify the relevant risk, select a procedure, and evaluate the resulting evidence.
Consider a hypothetical procurement audit. The objective is to assess whether purchases receive the required approval.
A useful practice prompt would ask which procedure best addresses that objective. Checking whether suppliers deliver on time might produce useful information, but it addresses a different risk. Exam preparation should train you to spot that mismatch.
For each answer, explain how the procedure connects to the objective. Then identify the weakness in the alternatives.
This is especially useful if your audit experience comes from one narrow area. Familiar procedures can feel persuasive even when the scenario requires a different approach.
Part 3: connect findings to management decisions
For Part 3, I'd practice decisions about the audit function, its plan, its quality, and what happens after an engagement produces findings.
Extend the hypothetical procurement example. An audit identifies approval weaknesses, and management agrees to corrective action. Your practice now shifts toward communicating the result, evaluating follow-up information, and determining the appropriate response if the issue remains unresolved.
The same business process appears in both illustrations. The decision changes.
If you already work in audit management, that broader perspective may feel familiar. If your work centers on testing and documentation, give extra attention to questions about function-level responsibilities.
For every practice scenario, write down who must act and which decision the question actually asks you to make.
Both parts share a time limit, but pacing needs practice
Part 2 and Part 3 have the same question count and time allowance in FreeFellow's current outline: 100 questions in two hours. Your preparation therefore needs a full-length pacing check for either part.
PrepPass
PrepPass's CIA Part 3 Study Guide describes a resource aligned with the Internal Audit Function syllabus effective in May 2025. Its listing specifies 175 original questions with worked explanations and a 100-question full-length practice exam.
PrepPass website screenshot for cia-part3
The same listing reports a Part 3 time limit of 120 minutes for 100 questions.
This is a concrete option to examine if you need a Part 3 question resource with explanations and a full-length exercise. The supplied description doesn't establish price or how closely its question difficulty matches the live exam. Evaluate a sample explanation before treating the resource as your main preparation tool.
Build around a 72-second average
Dividing 120 minutes by 100 questions gives an average of 72 seconds per question. That's a planning calculation, not a requirement to spend exactly that long on every item.
A simple practice checkpoint is 25 questions per 30 minutes. If you want review time at the end, your first pass must move faster than that average.
During a timed rehearsal, record whether you lose time reading the scenario, comparing plausible answers, or reconsidering completed questions. Each problem needs a different correction.
Use the distinction between flashcards and timed exams when choosing a study activity. Flashcards can rehearse recall; timed sets reveal whether you can make decisions within your available time.
Reserve a complete two-hour session for each rehearsal. Short quizzes won't show how your concentration changes across the full sitting.
Turn study hours into a calendar you can maintain
The cited resource descriptions don't establish a reliable average study time for either part. A useful estimate needs your starting knowledge, available weekly hours, and results on fresh practice questions.
I would begin with a small diagnostic across every domain. Review the explanations, including questions you answered correctly through guessing. Then build a provisional calendar.
Use the same starting budget to expose different priorities
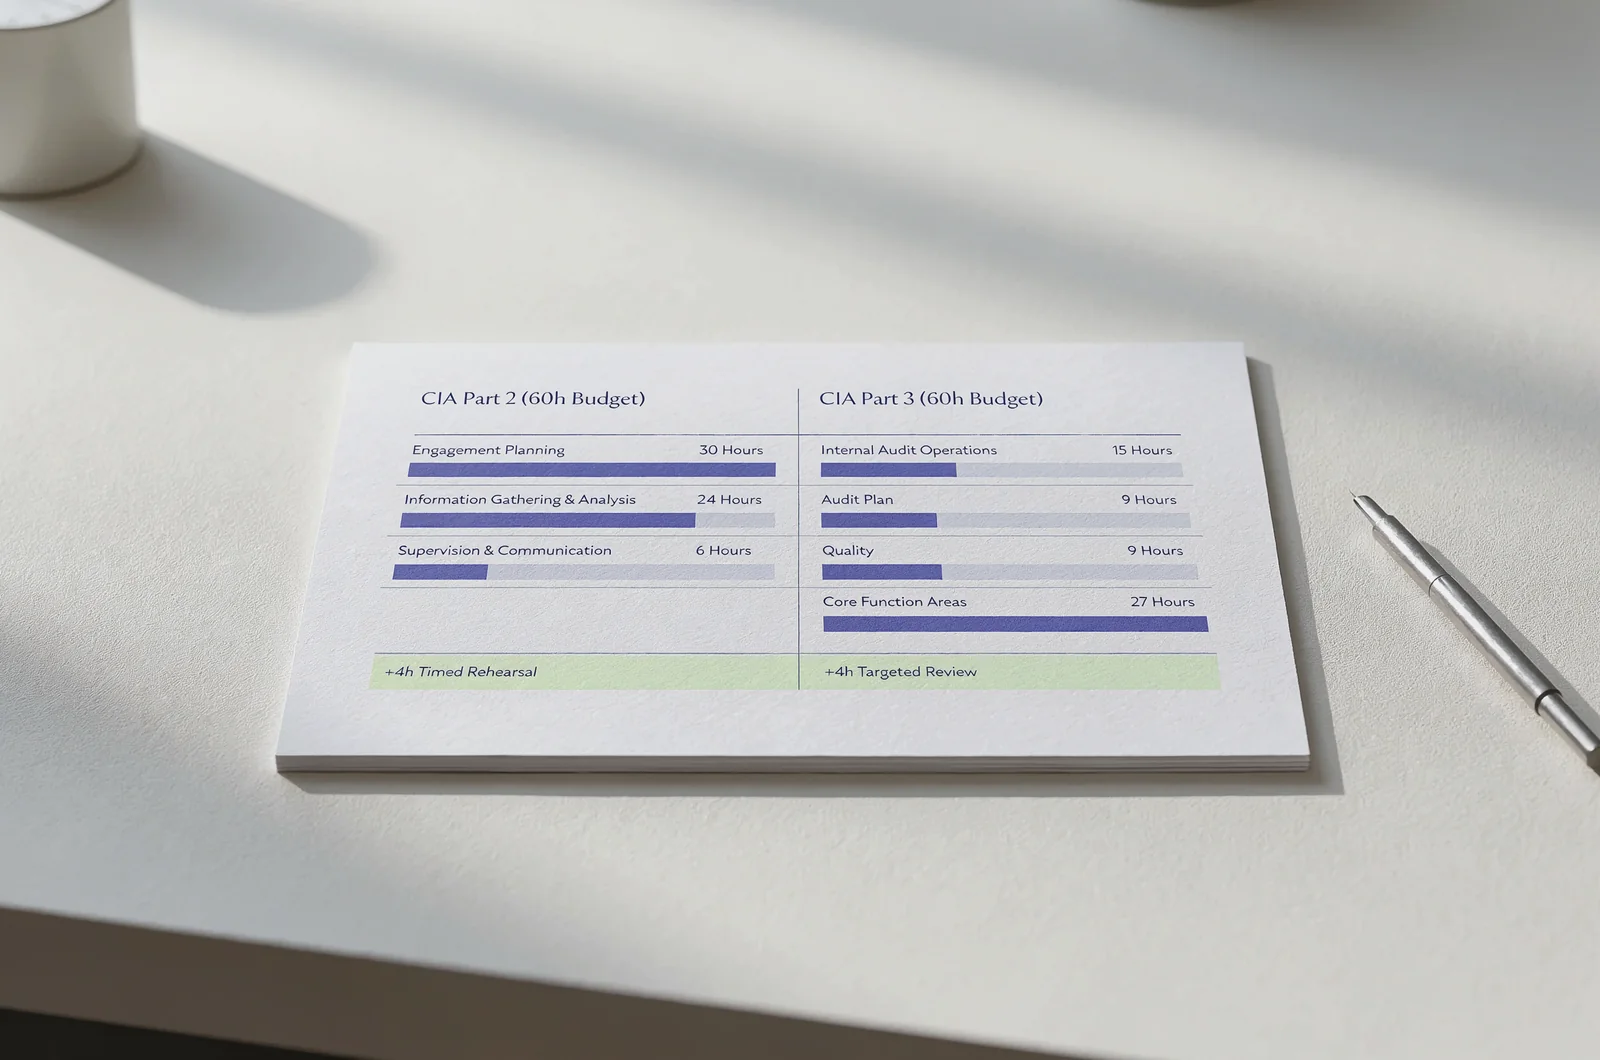
Here is an illustrative 60-hour content-review budget for each part. These are planning examples, not published candidate averages or IIA requirements.
Applying Part 2's domain weights gives:
- 30 hours for Engagement Planning.
- 24 hours for Information Gathering, Analysis, and Evaluation.
- 6 hours for Supervision and Communication.
Applying Part 3's weights gives:
- 15 hours for Internal Audit Operations.
- 9 hours for Internal Audit Plan.
- 9 hours for Internal Audit Function Quality.
- 27 hours for Engagement Results and Monitoring.
The equal total makes the difference in emphasis visible. Part 2 directs most of this example budget toward planning and evidence. Part 3 gives its largest allocation to results and monitoring.
Weights are a starting point for allocation. If a smaller domain contains your weakest material, increase its hours and reassess after another question set.
Add timed rehearsal and review separately
For either part, add two full-length rehearsals to the example budget. Two two-hour sittings require four hours.
If you also reserve two hours to review each rehearsal, the complete example becomes 68 hours: 60 for content review, four for timed practice, and four for rehearsal analysis.
At six hours per week, that is about 11.3 weeks. A 12-week calendar leaves a little room for disruption.
One workable six-hour week could contain four 30-minute evening sessions and two two-hour weekend sessions. Use the shorter blocks for explanations and recall. Protect a weekend block for longer question sets.
An interactive study-hours estimator could take weekly availability and remaining hours by domain, add rehearsal time, and calculate a tentative finish date.
Recalculate your calendar after the first rehearsal. Add time where unfamiliar questions still expose gaps.
Let errors determine the next week's work
Keep an error log with the domain, the reason for the miss, and the concept you need to revisit. Avoid copying entire explanations into notes.
Useful error categories include misunderstood responsibility, weak evidence selection, missed qualifiers, and excessive reading time. These categories are study labels, rather than official syllabus domains.
Use focused question practice to address one recurring problem at a time. After reviewing it, answer fresh questions on the same concept.
PrepHoot has study, timed, and flashcard modes across its catalog. Those modes suit different tasks in this plan; verify the syllabus coverage of any CIA resource before relying on it.
Allocate the next session to the error you can explain clearly but still repeat.
Carry concepts across parts without assuming question banks overlap
Part 2 and Part 3 share an audit context, but the supplied research doesn't establish a percentage of overlap between their question banks.
The outlines support conceptual connections. They don't prove that a question written for one part is suitable preparation for the other.
Reuse the reasoning behind a question
Engagement planning and function-level audit planning both involve decisions about risk and objectives. Evidence developed during an engagement can also influence how results are communicated and monitored.
These connections make previous study useful.
For the hypothetical procurement audit, keep one note explaining the approval risk and the purpose of the procedure. Then create separate notes for the engagement decision and the later response to the finding.
This gives you a reusable concept without treating the two parts as interchangeable.
After completing a question, state the responsibility it tests. If you can't identify that responsibility, review the relevant objective before doing another set.
Keep practice sets aligned with the part you intend to sit
A mixed bank can hide a coverage problem. A strong overall score may reflect repeated practice on familiar topics while a heavily weighted domain receives little attention.
For Part 2, inspect how the resource covers planning, evidence, and supervision. For Part 3, inspect coverage of operations, the audit plan, quality, and results and monitoring.
Ask whether explanations identify why each alternative fails. An answer letter alone gives you little help when the wording changes.
Track results separately by part and domain. Count a correct guess as an item requiring review, and record whether improvement holds on fresh questions.
Choose your study sequence from your current responsibilities
Part 2 is a sensible first study focus if you need to strengthen engagement objectives, procedure selection, evidence evaluation, and workpaper reasoning.
Part 3 may be a sensible first study focus if your work already includes audit planning, quality activities, reporting, or monitoring corrective action.
These are study-sequence recommendations. Confirm current program and scheduling requirements before booking.
For a working professional, the stronger starting point isn't automatically the easier-looking exam. It is the part whose responsibilities you can connect to real work while still covering every domain.
If you perform audit testing regularly, Part 2 may let you use familiar situations to learn exam reasoning. Check whether your experience also covers planning; the example budget assigns that domain half the content-review time.
If you support an audit plan or reporting process, Part 3 may give you useful context. Diagnose quality and operations separately rather than assuming management exposure covers the whole outline.
For a retake, concentrate on the part you need to complete. Use diagnostic errors to decide how much content review belongs before the next timed rehearsal.
When the choice remains close, compare two short, unfamiliar question sets, one from each part. Examine the explanations and classify the gaps. Choose the study sequence that fits your experience and available calendar, then reassess after the first full-length rehearsal.
Questions that affect your CIA study sequence
The Part 2 versus Part 3 decision usually comes down to difficulty, transferable study, and readiness. Keep those judgments tied to your own evidence.
Is Part 3 harder than Part 2?
The supplied evidence doesn't support a universal difficulty ranking. Part 2 emphasizes engagement planning and evidence decisions. Part 3 emphasizes function-level responsibilities and results. Your experience can make either set of responsibilities more familiar. Compare errors by domain before deciding which needs more time.
Can one resource prepare me for both parts?
A resource can support both if it clearly separates their current objectives and provides suitable practice for each. Shared terminology alone isn't enough. Check the version, domain coverage, explanations, and full-length format for each part before combining your preparation.
How do I know whether my study-hour estimate is enough?
Use unfamiliar questions and a complete timed rehearsal. Review guessed answers, repeated errors, and unfinished items. The 68-hour example is a calendar model, not a readiness threshold. Extend the plan when you still can't explain the reasoning behind a correct answer.
Should I spend equal time on every domain?
Start with the published weights, then adjust for your weaknesses. Equal allocation would give too little attention to some large domains. Revisit smaller domains when diagnostics show persistent errors, and check them again with fresh questions.
Keep CISA domain planning separate
Try the free sample questions, then create a free account or purchase full access or a membership for the exam they are preparing for. Get started |  |